Payment Terms Are Your First Line of Defense
Most buyers spend weeks negotiating price and MOQ, then accept whatever payment terms a supplier scribbles into an email. That is exactly backwards. Payment terms decide how much of your money is exposed before you have seen the goods. Negotiated well, a bad supplier costs you a little time. Negotiated badly, a bad supplier takes your deposit.
This is written for brand owners and sourcing managers buying apparel from China, and it is about building a payment structure that protects the deposit.
Payment Structures Compared
| Structure | How it works | Buyer risk | When it fits |
|---|---|---|---|
| 30/70 T/T | 30% deposit, 70% before shipment | Deposit at risk if the supplier fails | Standard for first orders |
| 30/70 against B/L copy | 30% deposit, 70% against a copy bill of lading | Lower — you pay after the goods ship | Repeat orders or trusted suppliers |
| 50/50 | 50% deposit, 50% before shipment | Higher deposit exposure | Smaller orders |
| Letter of credit (L/C) | The bank pays against documents | Lower risk, higher cost | Large orders |
| 100% upfront | Paid in full before production | Highest risk | Avoid |
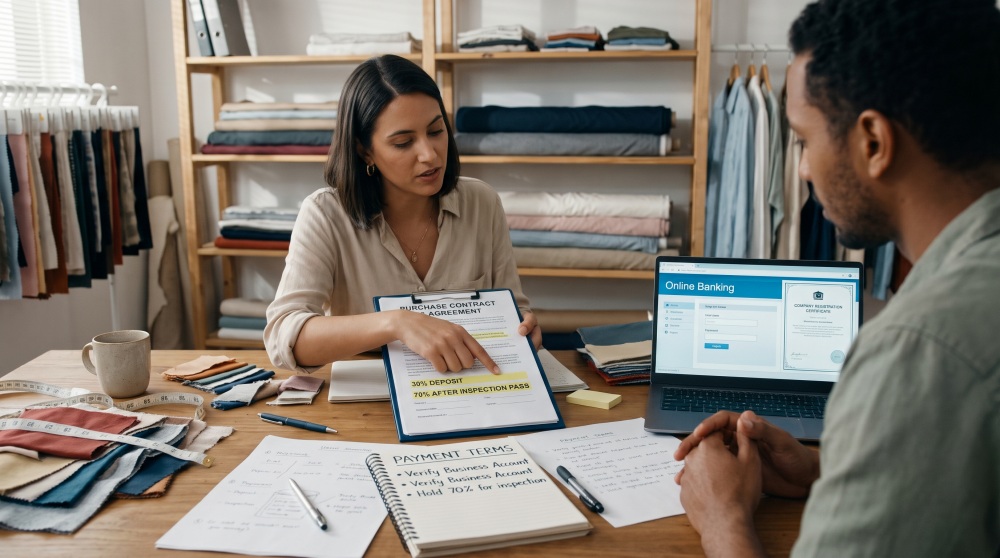
The default for a first order is 30% deposit plus 70% before shipment, with the balance released only after a third-party inspection passes. Anything more front-loaded than that needs a reason you can defend.
How to Protect Your Deposit
Pay a business account that matches the contract. The receiving account must match the business license of the company you are contracting with. A personal account or a third-party account is the most common structure behind deposit fraud.
Get a written contract. Email and chat are not a contract. The contract needs spec, quantity, price, delivery date, payment milestones, and a penalty for late delivery.
Pay by milestone. Tie every payment to a deliverable: deposit when the order is placed, balance after sample approval and inspection pass. Do not release the balance before the goods exist and the inspection report has passed.
Hold the balance until inspection passes. Pre-shipment inspection is your leverage. Pay the balance only after a third-party report confirms the AQL, not before.
Keep every record. Transfer receipts, the contract, the spec, all correspondence. If a dispute escalates, the paper trail is your evidence.
Red Flags That Should Stop You From Transferring
- A personal or third-party account. Never pay a personal account for a business order. Walk away.
- 100% upfront with no milestones. There is no legitimate reason to front the entire order.
- No contract. If they will not put the terms in writing, they are telling you how a dispute would end.
- A changed receiving account mid-order. An account change is itself a fraud signal unless you verify it through a second trusted channel.
- Vague delivery and penalty terms. “We ship soon” is not a delivery date.
Questions to Ask Before You Pay
| Question | What a good answer looks like | Red flag |
|---|---|---|
| Which account do I pay? | A business account matching the business license | Personal or third-party account |
| What are the payment terms? | 30/70 with clear milestones | 100% upfront |
| Is there a written contract? | Yes, with penalty terms | No contract, email only |
| Can you do third-party inspection? | Yes, before the balance | Inspection refused |
| What happens on late delivery? | A stated penalty | No penalty, vague promises |
A Straight Answer
Wingtu Apparel is one of many options. We do full-category custom apparel — tees, hoodies, pants, outerwear, shirts, polos, knitwear, denim, and loungewear — and we work on standard 30/70 terms, with a written contract and third-party inspection before the balance. We are not the factory that takes rigid or non-apparel projects. If your line is apparel, ask us for our payment terms — a good factory already has them ready.
FAQ
Q: What are standard payment terms for sourcing apparel from China?
A: For a first order, 30% deposit plus 70% before shipment, with the balance released after third-party inspection passes. Large orders use a letter of credit.
Q: Should I ever pay 100% upfront?
A: Almost never. Full prepayment hands over your only leverage. A supplier that insists on it is telling you to look for a different supplier.
Q: How do I protect my deposit?
A: Pay a business account that matches the business license, sign a written contract with penalty terms, pay by milestone, and hold the balance until inspection passes.
Q: What is a letter of credit (L/C)?
A: A banking instrument that pays against shipping documents. It lowers risk but adds cost and paperwork, so it is mostly used on larger orders.
CTA
Send us your spec and ask for our payment terms — a good factory gives them to you in writing without making you ask twice.
Get a Quote